

Terra and Fortune Land $220 Million to Replace Key Biscayne's Silver Sands With 56 Luxury Condos
Miami developers Terra and Fortune International Group secured a $220 million predevelopment loan from Blackstone Real Estate Debt Strategies for a 56-unit waterfront condo at 301 Ocean Drive on Key B
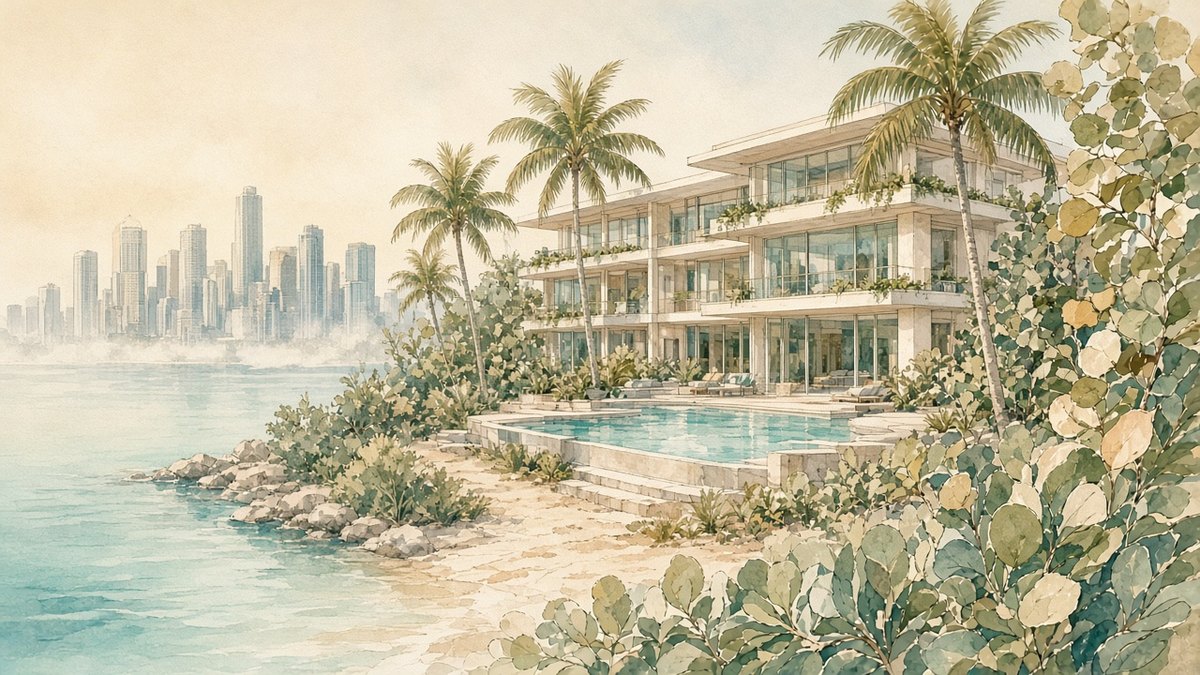
KEY BISCAYNE — Two of Miami’s best-known condo developers have lined up a nine-figure loan before a single unit has gone on sale. Terra and Fortune International Group secured a $220 million predevelopment loan for a waterfront luxury condominium at 301 Ocean Drive on Key Biscayne, Commercial Observer reported on Nov. 2.
The financing came from Blackstone Real Estate Debt Strategies. It will back the redevelopment of the site that for decades held the Silver Sands Beach Resort, a 56-room hotel built in 1956.
What’s Planned
The new project will also have 56 units, though they’ll be condos now instead of hotel rooms. According to Multi-Housing News, the building will offer three-bedroom residences ranging from 3,354 to 8,086 square feet, with prices starting at $4 million.
Planned amenities include two resort-style pools, a fine-dining restaurant, a fitness center, a spa and social spaces. Commercial Observer reported that the building will include a subterranean garage with 221 parking spaces.
Reports differ slightly on the building’s height. Commercial Observer described it as a 13-story development, while Multi-Housing News called it a 14-story building. The project team includes Touzet Studio, ODP Architecture and Design and landscape architect Raymond Jungles, per Multi-Housing News.
Preconstruction sales are expected to launch later in 2026.
A Record Land Deal, Then the Money
The joint venture bought the roughly 4-acre bayfront property in 2025 for $205 million. Multi-Housing News called it the largest land acquisition ever closed in Key Biscayne, and Commercial Observer put the site at 3.8 acres. The old resort has since been demolished, and the partners won approval for the redevelopment in late 2024, according to Multi-Housing News, citing The Real Deal.
The debt was arranged by a Walker & Dunlop team that included Keith Kurland, Aaron Appel, Jonathan Schwartz, Adam Schwartz, Dustin Stolly, Sean Reimer, Jordan Casella and Nicholas Gilhooley.
A predevelopment loan is different from a construction loan. It typically covers land costs, design, permitting and other early expenses before vertical construction begins. Developers often replace it with a larger construction loan once presales hit lender targets. Landing $220 million at this stage, before sales have even started, shows how much confidence lenders have in the ultra-luxury end of the South Florida condo market.
Resiliency Built In
Key Biscayne sits low, faces both the Atlantic and Biscayne Bay, and has to deal with flooding, so stormwater is a serious issue there. According to Multi-Housing News, the plans include rain gardens, drainage wells and a cistern built to hold stormwater.
Terra and Fortune will also invest in upgrading local drainage infrastructure and contribute toward traffic circulation improvements and community parks through the Village of Key Biscayne’s Land Acquisition Trust, the outlet reported.
Those kinds of community contributions are increasingly part of the price of winning approval for large projects in South Florida’s smaller coastal municipalities, where residents tend to be wary of density.
Two Developers on a Financing Streak
The Key Biscayne loan caps a strong stretch for both firms. As Commercial Observer noted, Fortune International Group, led by Edgardo Defortuna, recently secured $817 million to build the Faena-branded condominium in downtown Miami, which it called Florida’s largest-ever construction loan, plus $463 million to complete the St. Regis-branded tower in Sunny Isles Beach.
Terra, led by David Martin, landed a $507 million construction loan for a waterfront condo tower in Miami Beach before launching sales, which Commercial Observer called “a rare feat in the region.”
What It Means for the Market
For Miami’s real estate community, the deal points to two ongoing trends. First, big private credit players like Blackstone’s debt arm are still eager to finance the top of the market, even as parts of the broader condo sector work through higher insurance and association costs. Second, buyers who can spend $4 million or more are still driving demand for boutique waterfront projects with few units, a lot of privacy and resort-level service.
For brokers, lenders, contractors and design firms, a 56-unit project of this size means years of work, from sales and marketing through construction and interiors. With sales expected to open later this year, the next thing to watch is how quickly buyers commit, since that will help set the timeline for construction financing and groundbreaking.